Financial Planning / Education
How Inflation Affects Your Long-Term Savings in Singapore
Educational article
This article is generic financial education based on public sources. It is not a product recommendation or personal financial advice.
Quick answer
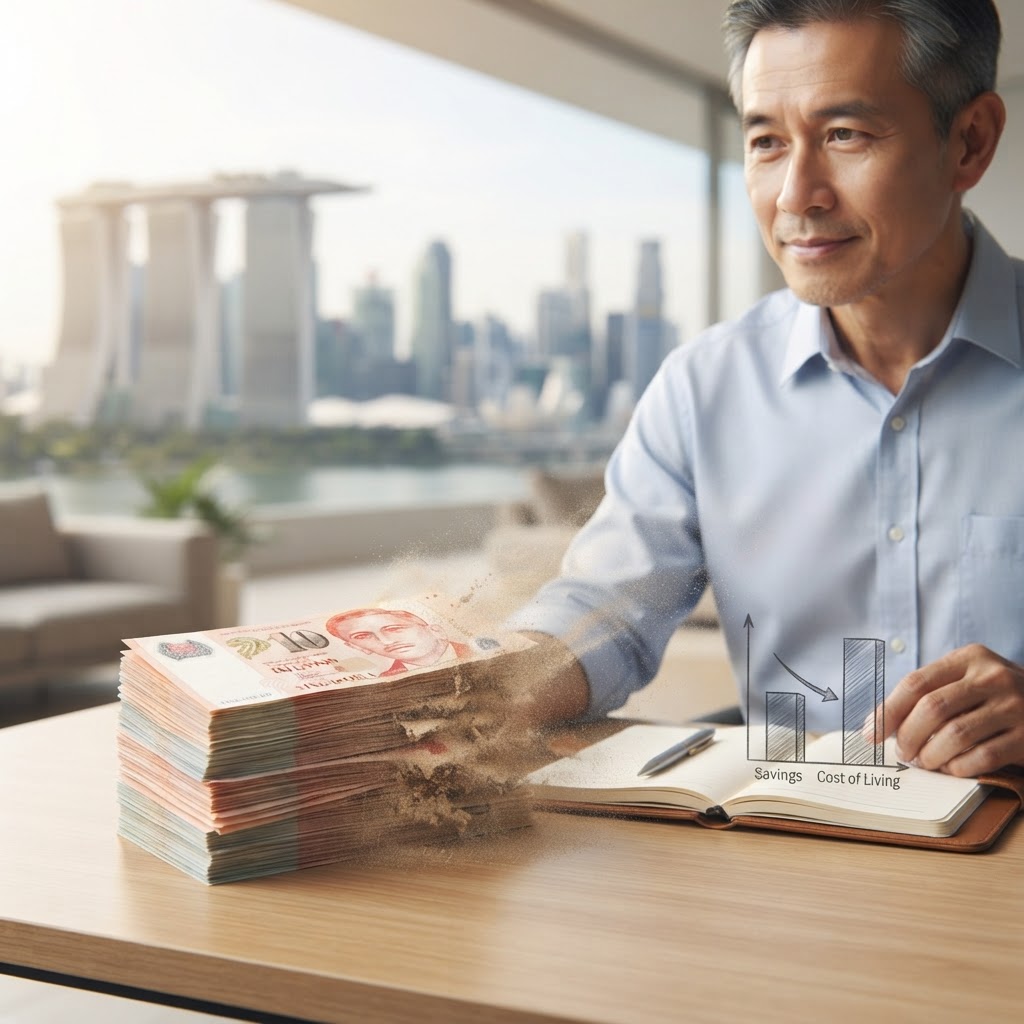
Inflation reduces the purchasing power of your money over time, meaning that if your savings do not grow at a rate equal to or higher than the rising cost of goods and services, the real value of your money effectively shrinks.
Have a question about your own situation?
If this article raised a question about your own situation, you can message Danny directly and ask what information would be useful to prepare before a proper discussion.
Written by
Danny ChuaFinancial Consultant · Representing Prudential Assurance Company Singapore (Pte) Limited
MAS Representative Number CCS300848890 · BSc. Pharm. Sci.
Published 2026-10-07 · Updated 2026-10-07
Understanding the Silent Erosion of Purchasing Power
Inflation is the rate at which the general level of prices for goods and services rises over time. When inflation occurs, each dollar you have saved buys less than it did previously. For many Singaporeans, this creates a hidden challenge: even if the number in your bank account stays the same or grows slowly through interest, your ability to afford the same lifestyle in the future may decrease.
Think of it as a race. If the cost of living rises by a certain percentage each year, your savings must grow by at least that same percentage just to stand still. If your money sits in an account earning interest lower than the inflation rate, you are effectively losing purchasing power every year.
The Mechanism of Inflation and Savings
To see how this works, imagine the cost of daily necessities. If a basket of goods costs a certain amount today, inflation means that same basket will likely cost more in the future. If your savings are kept entirely in cash or basic savings accounts, they may not keep pace with these price increases.
When considering the relationship between savings and investments, accessible cash and existing commitments are separate questions from inflation. An explanation of how much emergency cash you need before investing in Singapore can help distinguish immediate cash needs from long-term goals. The discussion of whether you should pay down debt before you start investing, explains another separate planning consideration; neither question implies a personal recommendation to invest.
Why Long-Term Planning Matters
Many people feel overwhelmed by the jargon surrounding investing, but the core concept is simple: investing is a way to potentially grow your money over the long term to counter the effects of inflation. Cash savings and investments serve different purposes. Access conditions, credit risk and any applicable deposit-insurance coverage depend on the institution, account and currency. An investment may rise or fall in value, and a return above inflation is not guaranteed.
When you are ready to explore options, remember that why liquidity matters before choosing a long-term investment is a key consideration. You need to balance the need for growth with the need to access your funds if your circumstances change. Furthermore, if you are looking at insurance as part of your planning, understanding the differences in term vs whole life insurance in Singapore can help you decide how to protect your family while managing your long-term financial commitments.
What to Look for in an Individual Financial Planner
If you decide to seek professional guidance, look for a planner who:
- Explains concepts in plain language without jargon.
- Asks about your specific goals, time horizon, and comfort with risk before discussing any products.
- Is transparent about the fact that investment values can fall and policy illustrations are projections rather than promises.
- Is easy to contact and willing to work around your schedule.
About Danny Chua's Service Approach
Danny Chua is a Financial Consultant in Singapore representing Prudential Assurance Company Singapore (Pte) Limited (MAS Representative Number CCS300848890). He focuses on providing clear, patient financial education to help individuals make informed decisions. Danny is reachable via WhatsApp, phone, or email. He understands that many clients have demanding work schedules and is happy to arrange discussions during evenings, weekends, or public holidays, subject to availability. Please note that formal transactions and policy processing remain subject to standard business hours.
Frequently Asked Questions
Does inflation mean I will lose money in my bank account?
Inflation describes changes in prices; it does not itself deduct money from a bank account. The account balance can separately change because of withdrawals, fees, interest or other account events. Purchasing power falls when price increases exceed the growth of that balance.
Is it better to keep all my money in fixed deposits?
A fixed deposit has its own interest rate, term and withdrawal conditions. Compare those terms with the date the money is needed and the relevant risks. Its interest may or may not keep pace with inflation; this article does not recommend a deposit or investment allocation.
Can I beat inflation without taking any risks?
There is no general promise that an investment will outpace inflation. Different arrangements have different risks, fees and access conditions. Diversification can reduce concentration-specific risk but cannot eliminate investment losses or guarantee a positive real return.
How do I start if I feel overwhelmed?
Start by reviewing your current savings and identifying your goals. You do not need to do everything at once. If you want to clarify this before deciding what to do next, you can WhatsApp Danny or request a conversation. Discussions can be arranged around work schedules, subject to availability.
Key Takeaways
- Inflation changes purchasing power; a nominal bank balance and its real value are different measures.
- Savings interest and investment returns may or may not keep pace with inflation.
- Investment values can fall, and no positive real return is guaranteed.
- Cash access, existing commitments, investment risks and fees remain separate planning considerations.
Sources
- What is inflation? - MoneySense (accessed 2026-10-07)
- What is investing? - MoneySense (accessed 2026-10-07)
- Financial advisory process - MoneySense (accessed 2026-10-07)
About Danny
Danny Chua is a Financial Consultant Representing Prudential Assurance Company Singapore (Pte) Limited. MAS Representative Number CCS300848890. Qualification: BSc. Pharm. Sci.. Read more about Danny.
Related Guidance
Prudential Assurance Company Singapore (Pte) Limited (PACS) is the insurer referred to in this disclaimer. Investment products are subject to investment risks including the possible loss of the principal amount invested. The figures stated relating to PACS products are for illustrative purposes only. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. We recommend that you seek advice from a PACS Financial Consultant before making a commitment to purchase a Prudential policy.
This advertisement has not been reviewed by the Monetary Authority of Singapore. Investment products are subject to investment risks including the possible loss of the principal amount invested. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. Seek advice from a Prudential Financial Consultant before making a commitment. This is Danny Chua's personal professional website and is not Prudential's official corporate website.