Investment-Linked Policies / Education
How Indexed or Benchmark-Linked Returns Work in an Investment-Linked Plan
Educational article
This article is generic financial education based on public sources. It is not a product recommendation or personal financial advice.
Quick answer
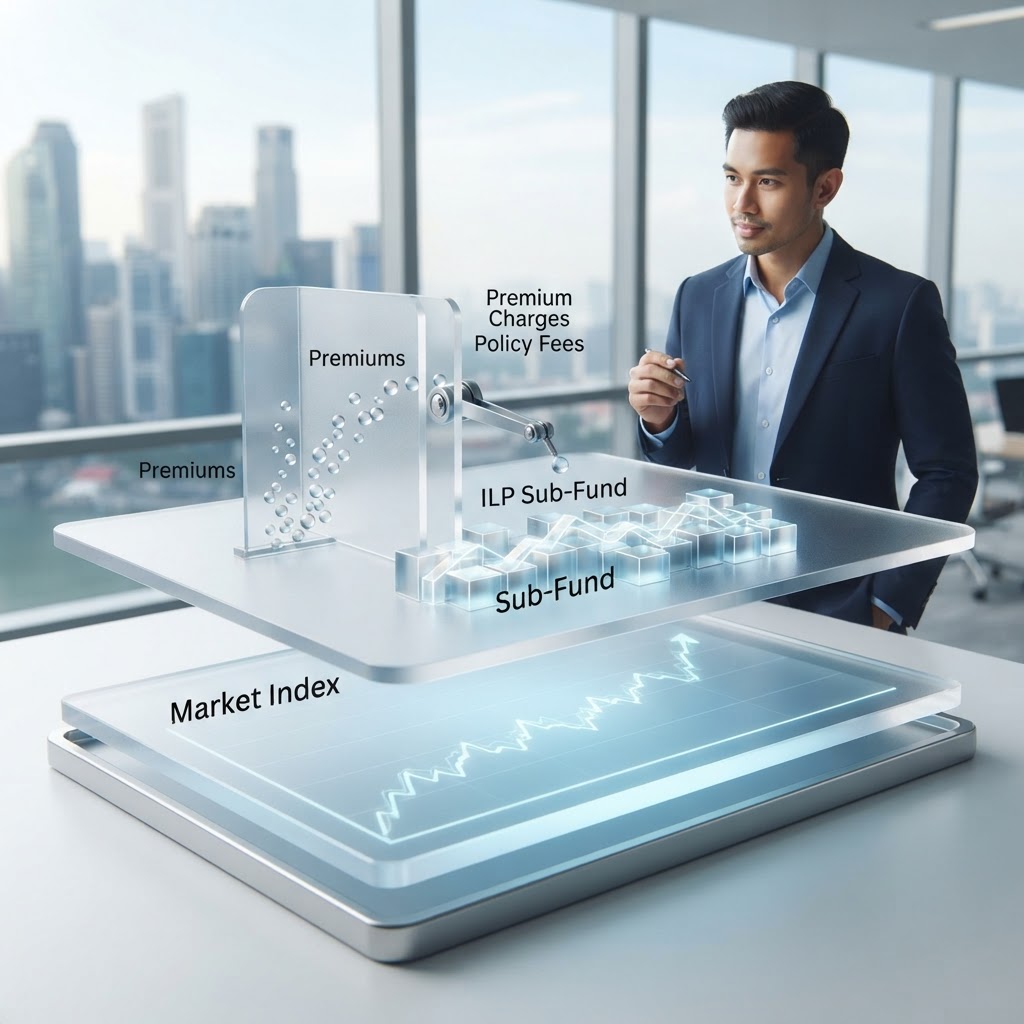
An ILP sub-fund may track an index, use a benchmark only as a performance reference, or be actively managed without trying to replicate that benchmark. A benchmark return is therefore not a guaranteed policy return. Your ILP value depends on the sub-fund units you hold and is affected by market performance, fund expenses and policy-level charges; MoneySense states that ILP returns and cash values are not guaranteed.
Have a question about your own situation?
If this article raised a question about your own situation, you can message Danny directly and ask what information would be useful to prepare before a proper discussion.

Written by
Danny ChuaFinancial Consultant · Representing Prudential Assurance Company Singapore (Pte) Limited
MAS Representative Number CCS300848890 · BSc. Pharm. Sci.
Published 2026-09-10 · Updated 2026-10-24
For someone new to investing in Singapore, words such as “index”, “benchmark” and “tracking” can sound interchangeable. They are not.
An investment-linked policy (ILP) invests premiums, after any applicable allocation and charges, into one or more sub-funds. The value of the policy depends on the units held in those sub-funds and can rise or fall with their performance. MoneySense states that ILP investment returns and cash values are not guaranteed.
Benchmark does not automatically mean index-tracking
A benchmark is a reference point used to assess or describe investment performance. A sub-fund can use a benchmark without being designed to reproduce it exactly.
An index-tracking strategy is narrower: it is designed to follow an index as closely as its stated mandate allows. Other sub-funds may be actively managed against a benchmark, while some may have no benchmark at all.
That distinction matters. If a fund document names an index, do not assume the fund must deliver the same return as that index. Check the stated investment objective and strategy in the Product Highlights Sheet, fund summary or other official fund documents.
Why an index or benchmark return is not your ILP return
Even where a sub-fund genuinely follows an index, several layers can cause your policy value to differ from the headline index movement.
- Fund-level expenses and implementation differences. A fund incurs expenses and may not hold or rebalance assets in exactly the same way as the published index methodology.
- Tracking difference and tracking error. Some index-oriented funds disclose the risk that their performance may not track the index precisely. A Prudential fund information booklet, for example, identifies tracking error risk arising from factors including investment strategy, fees and expenses. This is a product-specific example, not a rule that every ILP sub-fund is index-tracking.
- Policy-level charges. MoneySense explains that ILPs can include insurance coverage charges, policy administration charges and fund management fees. These charges can reduce the number or value of units supporting the policy.
- Market movement. Because ILP returns depend on sub-fund performance, the policy value can fall as well as rise.
Tracking difference and tracking error are not the same thing
Where an index-tracking fund actually reports these measures, they describe different things.
Tracking difference describes the performance gap between a fund and its benchmark over a period.
Tracking error describes how much that return gap varies over time. A Prudential fund booklet describes tracking error as the risk that an underlying fund’s performance may not track its index and notes that fees, expenses and the investment strategy can contribute to that difference.
Not every ILP sub-fund publishes these measures, so do not assume they will appear in every Product Highlights Sheet or policy document.
The ILP cost layer
MoneySense explains that not all premiums paid into an ILP necessarily purchase units; the proportion used is commonly described as the premium allocation rate. ILPs may also involve insurance coverage charges, policy administration charges and fund management fees.
MoneySense also notes that insurance charges can rise with age and that units may be sold to meet those charges. This means the return of the underlying sub-fund and the change in your overall policy value are different calculations.
Early surrender can also produce a cash value below total premiums paid, so a strong period for an index or sub-fund does not automatically mean a policyholder will receive the same percentage gain on surrender.
What to check in your own documents
Before treating a benchmark number as meaningful to your policy, check:
- Investment objective and strategy — does the sub-fund actually aim to track an index, or does it simply compare performance with a benchmark?
- Official fund documents — review the Product Highlights Sheet and fund summary for investment strategy, risks, fees and any benchmark information.
- Policy charges — identify premium allocation, insurance coverage charges, administration charges and fund-level fees that may affect policy value.
- Policy Illustration and Policy Contract — understand how charges and non-guaranteed values are presented for the specific policy.
- Current statements — compare the value and number of units held with the charges deducted through the policy.
The practical takeaway is simple: an index or benchmark is a reference or investment mechanism, not a promise of what your ILP will be worth. Read the fund mandate and the policy cost structure separately, because both influence the result.
If you are reviewing an existing ILP, you can ask Danny a question about which documents and figures to locate before deciding whether any personalised review is needed.
Key Takeaways
- A benchmark is a performance reference; it does not automatically mean the sub-fund is designed to track that index.
- An index-tracking sub-fund can still differ from its index because of investment implementation, fees, expenses and tracking effects.
- ILP policy value can differ from sub-fund performance because policy-level insurance and administration charges also affect the units held.
- MoneySense states that ILP investment returns and cash values are not guaranteed.
- Check the fund’s stated objective and strategy, Product Highlights Sheet, policy charges and Policy Contract rather than assuming a benchmark return equals your policy return.
Sources
- Understanding investment-linked insurance policies - MoneySense (accessed 2026-09-10)
- Investment-linked policies: Guide to fees and pricing - MoneySense (accessed 2026-09-10)
- Investment-linked versus participating life insurance policies - MoneySense (accessed 2026-09-10)
- PRULink Fund Information Booklet – PRULink FlexGrowth Fund (SGD) - Prudential Singapore (accessed 2026-09-10)
About Danny
Danny Chua is a Financial Consultant Representing Prudential Assurance Company Singapore (Pte) Limited. MAS Representative Number CCS300848890. Qualification: BSc. Pharm. Sci.. Read more about Danny.
Related Guidance
Prudential Assurance Company Singapore (Pte) Limited (PACS) is the insurer referred to in this disclaimer. Investment products are subject to investment risks including the possible loss of the principal amount invested. The figures stated relating to PACS products are for illustrative purposes only. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. We recommend that you seek advice from a PACS Financial Consultant before making a commitment to purchase a Prudential policy.
This advertisement has not been reviewed by the Monetary Authority of Singapore. Investment products are subject to investment risks including the possible loss of the principal amount invested. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. Seek advice from a Prudential Financial Consultant before making a commitment. This is Danny Chua's personal professional website and is not Prudential's official corporate website.