Investment-Linked Policies / Education
How ILP Charges Are Deducted From Your Premium in Singapore
Educational article
This article is generic financial education based on public sources. It is not a product recommendation or personal financial advice.
Quick answer
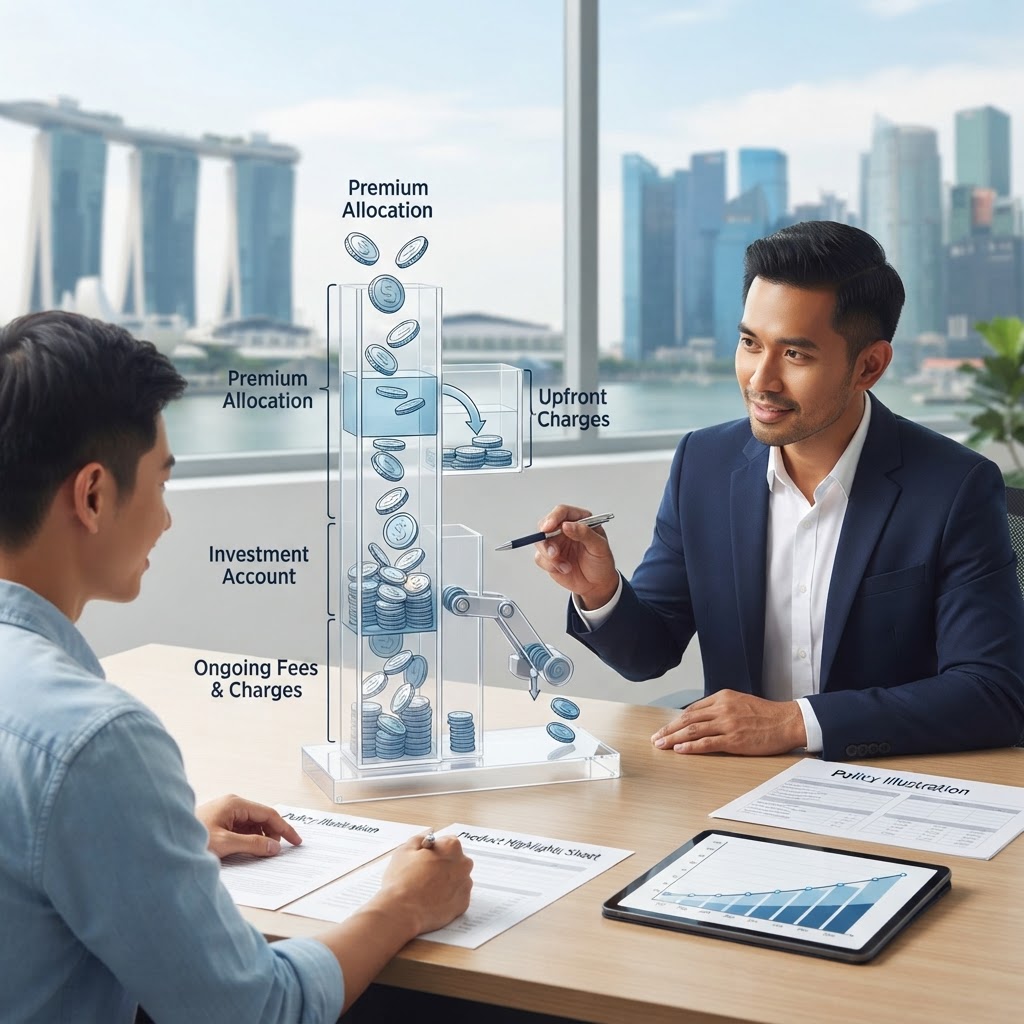
In an Investment-Linked Policy (ILP), charges are typically deducted either by taking a portion of your premium before it is invested or by selling units from your account, which directly impacts your total investment value over time.
Have a question about your own situation?
If this article raised a question about your own situation, you can message Danny directly and ask what information would be useful to prepare before a proper discussion.

Written by
Danny ChuaFinancial Consultant · Representing Prudential Assurance Company Singapore (Pte) Limited
MAS Representative Number CCS300848890 · BSc. Pharm. Sci.
Published 2026-10-19 · Updated 2026-11-12
Understanding the Mechanics of ILP Charges
When you purchase an Investment-Linked Policy (ILP), your premiums serve two purposes: providing insurance coverage and funding your investments. Because these are insurance products, they carry specific costs that are necessary to maintain the policy and the underlying sub-funds. Understanding these charges is essential for anyone looking to understand if an ILP is worth it.
Where to Find Fee Information
Every ILP comes with a Product Summary, a Product Highlights Sheet (PHS), and a Policy Illustration. These documents are your primary resources for identifying costs. The Policy Illustration, in particular, contains a table of deductions that maps out how charges impact your account value over time. If you are unsure how to interpret these, asking questions before buying an ILP is a standard and encouraged part of the process.
Common Types of ILP Charges
Charges are generally categorized by how and when they are applied:
- Distribution Costs: These cover the setup and acquisition of the policy. In many plans, these are front-loaded, meaning a larger portion of your early premiums goes toward these costs rather than into your investments.
- Insurance Charges: These pay for your death and disability coverage. Because the cost of insurance typically rises with age, these charges are often funded by selling units from your account. If you are curious about how this works, you can read more about ILP insurance meaning.
- Fund Management Fees: These are paid to the fund manager for overseeing the sub-funds you have selected. These are usually deducted from the sub-fund's asset value.
- Policy or Administration Fees: These cover the ongoing maintenance of your policy and are often deducted monthly.
- Surrender Penalties: If you terminate your policy early, you may be subject to a surrender charge, which is a percentage of your account value or premium that is deducted before you receive your payout.
What Does MoneySense Say About ILP Fees and Charges?
MoneySense, the Monetary Authority of Singapore's financial education programme, lists the main ILP charges in its guide to ILP fees and pricing, as of October 2026:
- Insurance coverage charges depend on the coverage amount, your age and whether you smoke, and they rise with age. They are deducted by selling units, as of October 2026 per MoneySense.
- Fund management fees are deducted from the sub-fund's net asset value before the unit price is calculated, as of October 2026 per MoneySense.
- Policy or administration charges are deducted from the monthly sale of units, as of October 2026 per MoneySense.
- The premium allocation rate is the share of each premium that is used to buy units; the rest is deducted upfront. MoneySense says it is stated in the Product Summary or Policy Contract (as of October 2026, MoneySense).
- The bid-offer spread is the gap between the price at which you buy units and the price at which you sell them. MoneySense says it is usually around 5% and covers distribution, marketing and general administration (as of October 2026, MoneySense).
MoneySense also says fees and charges may not be guaranteed and are subject to change, and that before you sell units you should make sure enough remain to sustain the insurance cover you want (as of October 2026, MoneySense). Check your own Product Summary, Product Highlights Sheet and Policy Contract for your plan's actual charges.
Why Early Premiums Are Not Fully Invested
In many regular premium ILPs, the insurer applies a 'premium charge' or uses a specific allocation structure. For example, in a front-end loaded policy, a portion of your premium is deducted upfront to cover distribution and administrative costs. Only the remainder is used to purchase units in your chosen sub-funds. This is why, in the early years of a policy, the cash value may be significantly lower than the total premiums you have paid. Over time, as these initial charges are satisfied, a higher percentage of your premium is typically allocated to purchasing units.
About Danny Chua's Service Approach
Danny Chua is an individual Financial Consultant in Singapore representing Prudential Assurance Company Singapore (Pte) Limited (MAS Representative Number CCS300848890). He focuses on providing clear, factual education to help individuals understand their financial options. Clients often value his accessibility and willingness to arrange discussions around demanding schedules, including evenings, weekends, and public holidays, subject to availability. You can reach Danny via WhatsApp, phone, or email to clarify these concepts or discuss your specific situation. Please note that formal transactions remain subject to standard business and processing hours.
Frequently Asked Questions
- How do I know if my ILP is front-end or back-end loaded? You can find this information in your Product Summary or by reviewing the premium allocation section of your Policy Illustration.
- Can I change my premium amount? Some policies offer flexibility, but you should always check your specific contract terms regarding premium flexibility to understand the impact on your coverage and charges.
- Are these charges fixed? While some charges are fixed, others—such as insurance costs—may increase with age or changes in your coverage needs. Always refer to your Policy Illustration for the most accurate projections.
- What happens if I stop paying premiums? Stopping premiums can lead to a policy lapse if there are insufficient units to cover ongoing charges. It is important to understand the consequences of a premium holiday before taking action.
If you want to clarify these charges before deciding what to do next, you can WhatsApp Danny or request a conversation. Discussions can be arranged around work schedules, subject to availability.
Key Takeaways
- ILP charges include distribution costs, insurance charges, fund management fees, and policy administration fees.
- Charges are typically deducted either upfront from your premium or by selling units from your account.
- Early-year surrender values are often lower because initial premiums are used to cover setup and distribution costs.
- Always review your Product Summary and Policy Illustration to see how specific charges impact your account value.
- Investment returns in an ILP are non-guaranteed and depend on the performance of your chosen sub-funds.
Sources
- Investment-linked policies: Guide to fees and pricing - MoneySense (accessed 2026-10-31)
- Understanding investment-linked insurance policies - MoneySense (accessed 2026-10-19)
- Financial advisory process - MoneySense (accessed 2026-10-19)
About Danny
Danny Chua is a Financial Consultant Representing Prudential Assurance Company Singapore (Pte) Limited. MAS Representative Number CCS300848890. Qualification: BSc. Pharm. Sci.. Read more about Danny.
Related Guidance
Prudential Assurance Company Singapore (Pte) Limited (PACS) is the insurer referred to in this disclaimer. Investment products are subject to investment risks including the possible loss of the principal amount invested. The figures stated relating to PACS products are for illustrative purposes only. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. We recommend that you seek advice from a PACS Financial Consultant before making a commitment to purchase a Prudential policy.
This advertisement has not been reviewed by the Monetary Authority of Singapore. Investment products are subject to investment risks including the possible loss of the principal amount invested. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. Seek advice from a Prudential Financial Consultant before making a commitment. This is Danny Chua's personal professional website and is not Prudential's official corporate website.