Investing Basics / Education
How Beginners in Singapore Can Understand Investment Risk Tolerance
Educational article
This article is generic financial education based on public sources. It is not a product recommendation or personal financial advice.
Quick answer
Investment risk tolerance is not a single score or personality label. For a beginner in Singapore, it is more useful to understand the factors that affect how much investment uncertainty you may be able and willing to accept—such as your goals, time horizon, liquidity needs, financial resilience, income stability and comfort with losses—without using an article to assign yourself a personalised risk profile or asset allocation.
Have a question about your own situation?
If this article raised a question about your own situation, you can message Danny directly and ask what information would be useful to prepare before a proper discussion.

Written by
Danny ChuaFinancial Consultant · Representing Prudential Assurance Company Singapore (Pte) Limited
MAS Representative Number CCS300848890 · BSc. Pharm. Sci.
Published 2026-09-09 · Updated 2026-09-09
Investment risk tolerance is not a single score or personality label. For a beginner in Singapore, it is more useful to understand the factors that affect how much investment uncertainty you may be able and willing to accept—such as your goals, time horizon, liquidity needs, financial resilience, income stability and comfort with losses—without using an article to assign yourself a personalised risk profile or asset allocation.
What does investment risk tolerance mean?
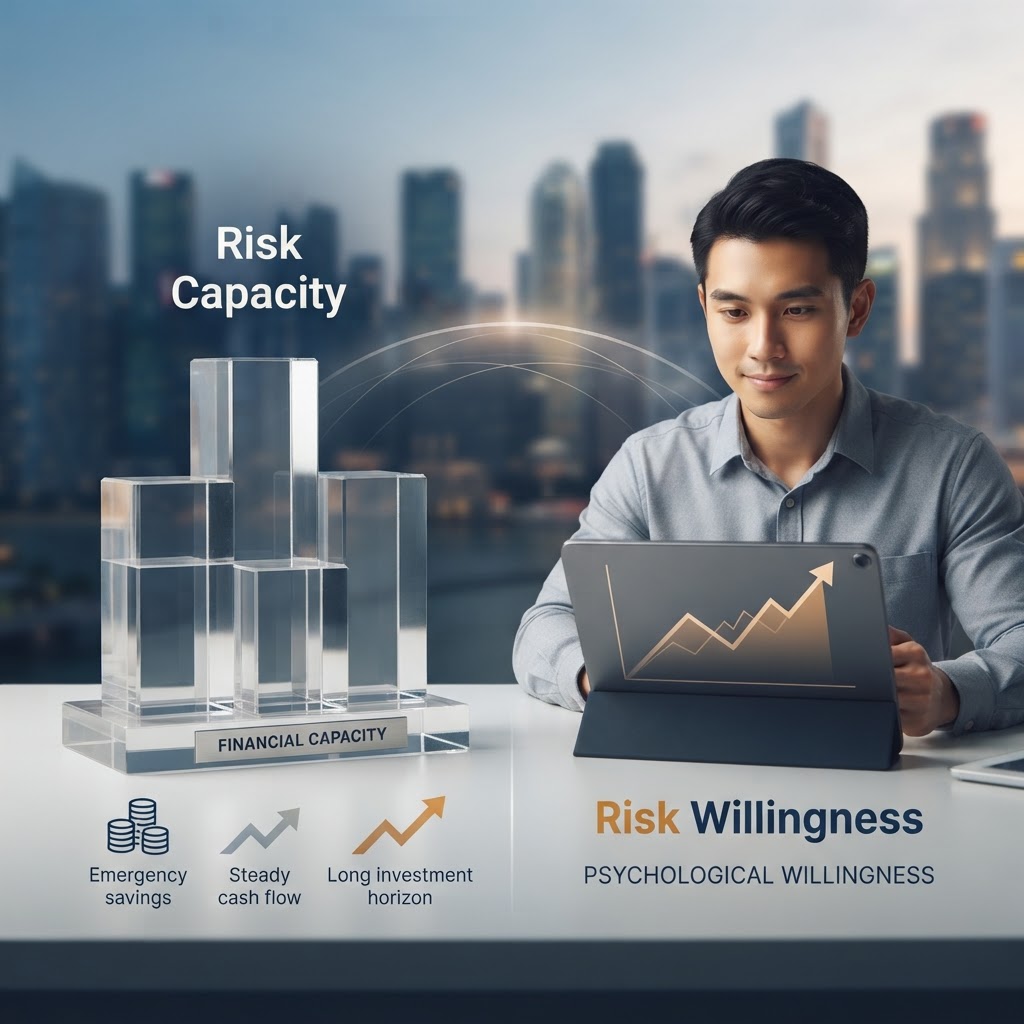
MoneySense explains that all investments involve risk and that a suitable investment should be considered in light of a person's needs, risk profile and circumstances. In plain language, risk tolerance is about how you respond to uncertainty and potential loss, while risk capacity is about whether your financial situation can absorb that uncertainty without undermining important commitments.
The two ideas are related, but they are not identical. Someone may feel comfortable with market volatility but still have limited financial room for losses because the money is needed soon. Another person may have substantial financial resources but still be uncomfortable with large fluctuations. Neither situation can be reduced to a universal rule from an article.
Risk capacity: what can your finances absorb?
Risk capacity is influenced by practical financial circumstances rather than confidence alone. Relevant factors can include:
- how soon the money may be needed;
- whether emergency cash is available;
- income stability and regular commitments;
- liabilities and dependants;
- other savings and financial resources; and
- how important the investment money is to a specific goal.
MoneySense's current investing guidance says a person should have enough money for daily and expected expenditure, emergency cash and basic health and life insurance in place before beginning an investing journey. Its July 2026 "What is investing?" page refers to about 3 to 6 months' income for emergency cash, while the Basic Financial Planning Guide uses at least 3 to 6 months' worth of expenses as a broader emergency-fund rule of thumb. These are differently scoped public references, so this article does not convert them into one universal personalised threshold.
The key educational point is simpler: money needed for near-term essentials generally has less room to absorb investment losses than money that is genuinely long term.
Risk appetite or willingness: how do you react to uncertainty?
Risk appetite describes how comfortable you feel with investment uncertainty and fluctuations. This can affect behaviour when markets fall.
Useful questions to think about include:
- Would a fall in value make you abandon a long-term plan immediately?
- Are you comfortable with an investment whose value can move up and down before your goal date?
- Do you understand that a higher potential return normally comes with greater risk of loss?
- Would uncertainty cause you to make decisions that conflict with the reason you invested in the first place?
These questions are prompts for reflection, not a scoring system. A general article cannot determine whether someone is "conservative", "moderate" or "aggressive", and it should not prescribe a portfolio allocation from those answers alone.
Why time horizon matters
Your investment time horizon is the period before you expect to need the money. MoneySense explains that a longer horizon gives an investor more time to stay invested through short-term fluctuations, while a shorter horizon can reduce the ability to absorb a market decline close to the date the money is needed.
A longer horizon does not guarantee that losses will recover, and age alone does not determine the right level of risk. MoneySense's September 2026 life-stage investing guidance also notes that risk decisions can depend on income stability, cash and CPF savings, family obligations, liquidity needs and personal circumstances—not simply age.
Liquidity is part of risk capacity
Liquidity means how easily and quickly an investment can be converted to cash. It matters because a person who may need money at short notice can face a different risk problem from someone investing money that is not needed for many years.
Before considering any long-term investment, understand:
- how quickly the money can be accessed;
- whether the value can fluctuate before withdrawal;
- whether fees or contractual restrictions can apply when exiting; and
- whether an unexpected cash need could force an early sale.
This is one reason risk capacity should not be treated as a personality quiz.
Where diversification fits
Diversification means spreading exposure rather than relying heavily on one security, sector, market or asset type. It can reduce concentration-specific risk, but it does not eliminate broad market risk or guarantee a profit.
Diversification also does not determine a personalised asset allocation. The amount allocated to different asset types should depend on the person's circumstances and, where personalised advice is being provided, an appropriate fact-find and suitability assessment.
A beginner-friendly way to prepare for a risk discussion
Instead of trying to assign yourself a label, prepare the information that affects a proper risk discussion:
- Write down the goal for the money and when it may be needed.
- Separate near-term spending and emergency resources from money intended for longer-term goals.
- List major liabilities, dependants and regular commitments that could affect your ability to absorb losses.
- Think about how you have reacted—or believe you may react—to financial uncertainty and falling values.
- Check the investment's liquidity, fees, downside risk and whether any returns or values are guaranteed or non-guaranteed.
- Revisit these factors when your circumstances change.
This process helps you understand the inputs to a risk assessment without pretending that one article can produce a personalised risk score.
Quick distinction: risk tolerance, risk capacity and risk profile
Risk tolerance describes your willingness or comfort with investment uncertainty. Risk capacity concerns your financial ability to bear losses without disrupting important goals. A risk profile is a broader assessment that may consider these factors together with objectives, time horizon, financial situation, knowledge and other relevant circumstances.
No single factor automatically determines a suitable investment or asset allocation.
The main takeaway
For a beginner, the useful question is not "What risk level should I choose?" but "What information affects my ability and willingness to take investment risk?" Goals, time horizon, liquidity, financial resilience, income stability and comfort with losses all matter. Any personalised recommendation or allocation should follow an appropriate assessment of the individual's circumstances rather than a universal rule from educational content.
New to investing and still unsure how these concepts apply? You can ask Danny a general question before deciding whether any next step is appropriate for you.
Key Takeaways
- Risk tolerance and risk capacity are related but different: one concerns comfort with uncertainty, while the other concerns the financial ability to bear losses.
- Goals, time horizon, liquidity needs, financial resilience, income stability and family commitments can all affect a risk assessment.
- A general article should not assign a conservative, moderate or aggressive profile or prescribe an asset allocation.
- A longer time horizon can provide more time to ride through short-term fluctuations, but it does not guarantee recovery or profit.
- Any personalised risk profile or investment allocation should follow an appropriate assessment of the individual's circumstances.
Sources
- What is investing? - MoneySense (accessed 2026-09-09)
- Life stage investing: Is it for me? - MoneySense (accessed 2026-09-09)
- Financial advisory process - MoneySense (accessed 2026-09-09)
- Basic Financial Planning Guide - MoneySense (accessed 2026-09-09)
About Danny
Danny Chua is a Financial Consultant Representing Prudential Assurance Company Singapore (Pte) Limited. MAS Representative Number CCS300848890. Qualification: BSc. Pharm. Sci.. Read more about Danny.
Related Guidance
Prudential Assurance Company Singapore (Pte) Limited (PACS) is the insurer referred to in this disclaimer. Investment products are subject to investment risks including the possible loss of the principal amount invested. The figures stated relating to PACS products are for illustrative purposes only. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. We recommend that you seek advice from a PACS Financial Consultant before making a commitment to purchase a Prudential policy.
This advertisement has not been reviewed by the Monetary Authority of Singapore. Investment products are subject to investment risks including the possible loss of the principal amount invested. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. Seek advice from a Prudential Financial Consultant before making a commitment. This is Danny Chua's personal professional website and is not Prudential's official corporate website.