Family Planning / Education
Family Protection Life Insurance in Singapore: How Much Do You Need?
Educational article
This article is generic financial education based on public sources. It is not a product recommendation or personal financial advice.
Quick answer
There is no single family-protection life-insurance amount that everyone in Singapore needs. A needs-based estimate adds the financial support your dependants may need, relevant liabilities and planned education costs, then subtracts resources that would actually be available to them. The result is a planning estimate—not an automatic recommended sum assured—and should be reviewed against your circumstances, existing cover, affordability and policy terms.
Want to check your own protection gap?
If you already know who depends on you and your main household commitments, you can ask Danny what information to prepare for a proper needs review.

Written by
Danny ChuaFinancial Consultant · Representing Prudential Assurance Company Singapore (Pte) Limited
MAS Representative Number CCS300848890 · BSc. Pharm. Sci.
Published 2026-08-27 · Updated 2026-10-15
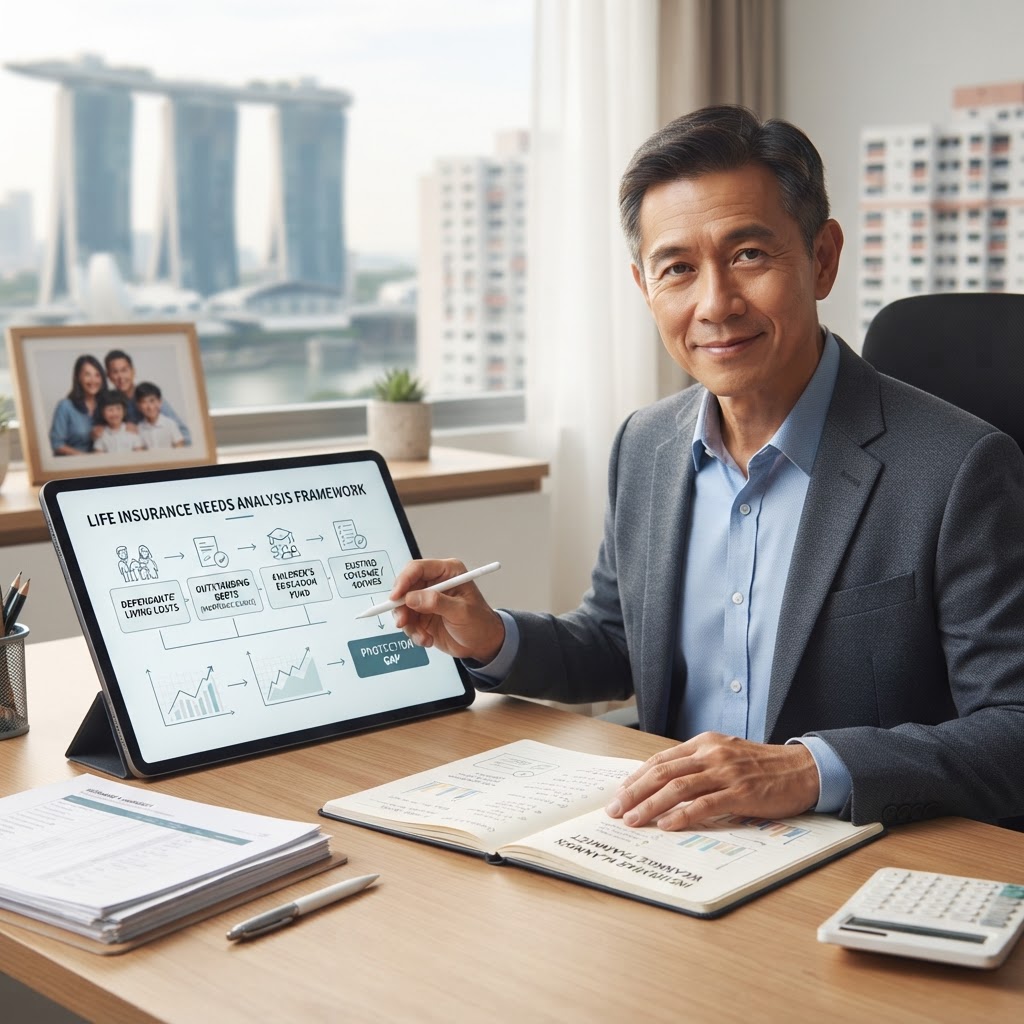
A useful way to estimate family-protection life insurance needs is to total the financial support your dependants may need, add relevant liabilities and planned education costs, then subtract resources that would actually be available to them. The result is a planning estimate that should be reviewed against your circumstances, existing cover and benefit conditions.
If you are new to financial planning, insurance terminology can feel overwhelming. A needs analysis does not have to begin with a product or a fixed salary multiple. It can begin with a simple question: what financial responsibilities would remain if your income stopped because of death?
This article provides a structured framework for estimating a protection gap. It is educational rather than a personal recommendation, and the figures you use should be checked against current policy terms, CPF records, loan balances and your family’s actual circumstances.
Moving Past a Simple Rule of Thumb
Rules of thumb based on a multiple of annual income can be a rough starting point, but they do not capture differences in dependants, debts, existing assets or how long support may be needed.
Two people with the same income can have very different family responsibilities. One may have no dependants or housing loan, while another may support children, parents and a mortgage. A needs-based estimate therefore starts with the obligations and resources that actually apply.
Step 1: Estimate Dependants’ Living Costs
Start by identifying who relies on your income and what portion of household spending you currently support. This may include a spouse, children or parents.
Consider recurring costs such as food, utilities, transport, healthcare and other essential household expenses. Then estimate how long each dependant may reasonably need support. Because future needs are uncertain, this should be treated as a planning estimate rather than an exact figure.
A simple baseline is:
Estimated annual support × estimated years of support
This does not account for every future change, but it gives you a transparent starting point that can be reviewed later.
Step 2: Review Outstanding Liabilities
Next, list debts that could affect your family’s finances, such as housing loans, car loans and other significant outstanding balances.
For an HDB housing loan, do not automatically assume that the entire balance needs to be added to the insurance gap. First check whether the Home Protection Scheme (HPS) applies, your insured share and the actual coverage or claim conditions. HPS is designed to protect against losing an HDB flat when an insured member dies, suffers terminal illness or total permanent disability, subject to the scheme’s terms and the member’s insured share.
If other mortgage insurance or loan-protection arrangements exist, check their actual benefits before counting the same liability twice.
Step 3: Consider Planned Education Support
If supporting a child’s future education is an important family goal, you may include a reasonable estimate of that planned support.
The amount can vary substantially depending on the type of education, location, timing and how much the family intends to fund. Rather than treating a current university fee as a guaranteed future cost, use a working estimate and revisit it over time.
Step 4: Subtract Resources That Would Actually Be Available
Now review resources that could reduce the financial gap. Depending on your circumstances, these may include:
- cash and deposits that would be available to the family;
- existing life-insurance death benefits, after checking the actual policy terms;
- employer-provided group insurance, while recognising that employment-related cover may change or end; and
- CPF savings that would be distributed after death according to CPF nomination rules or the applicable distribution process if there is no valid nomination.
CPF savings generally do not form part of a person’s estate and are not distributed through a will. A valid CPF nomination allows CPF savings to be distributed to nominated beneficiaries. If there is no valid nomination, CPF Board explains that distribution is handled through the Public Trustee under the applicable intestacy rules, while Muslim members are subject to the relevant Muslim inheritance rules. Check CPF Board’s current nomination guidance rather than assuming the same estate process applies to everyone.
A simple working estimate is:
Estimated family needs + relevant liabilities + planned education support − available resources = estimated protection gap
This is not an automatically recommended sum assured. It is a number to review together with affordability, existing policies, benefit definitions and other financial priorities.
Important Variables to Review
Inflation and Time Horizon
Costs can change over time, especially when support is expected for many years. A flat estimate is therefore only a baseline. Review the estimate periodically rather than treating it as permanently correct.
Death, Critical Illness and Disability Are Different Needs
This framework mainly addresses the financial impact of death. Critical illness and disability-related protection have different benefit triggers and purposes. Do not assume that a death benefit automatically provides the same protection for critical illness or loss of income through disability. Check the actual policy definitions and benefits separately.
Guaranteed and Non-Guaranteed Values
When counting existing insurance or investment values, distinguish guaranteed amounts from non-guaranteed projections. Non-guaranteed values can change and may be lower than illustrated, including potentially nil where the relevant benefit is not guaranteed.
Affordability Matters
A larger protection estimate does not automatically mean that buying more insurance is the right next step. Premium affordability, existing coverage, other financial priorities and policy terms all matter. The purpose of the calculation is to make the discussion more transparent, not to turn a formula into a product recommendation.
When to Revisit the Estimate
A protection-gap estimate can change after major life events such as having a child, taking on or repaying a mortgage, a change in income, changes in dependants’ needs, or a material change in existing insurance or assets.
If you are unsure how to interpret the framework, you can ask Danny a general question or review your current arrangements before deciding whether any next step is appropriate for you.
For a broader overview of how family protection planning fits together, see Family Protection Planning in Singapore.
Frequently Asked Questions
How do I estimate how much family-protection life insurance I need?
A useful way is to total the financial support your dependants may need, add relevant liabilities and planned education costs, then subtract resources that would actually be available to them. The result is a planning estimate that should be reviewed against your circumstances, existing cover and benefit conditions.
Is a multiple of annual income a good way to decide?
Rules of thumb based on a multiple of annual income can be a rough starting point, but they do not capture differences in dependants, debts, existing assets or how long support may be needed. A needs-based estimate starts with the obligations and resources that actually apply.
Do I need to cover my whole HDB housing loan?
Do not automatically assume that the entire balance needs to be added to the insurance gap. First check whether the Home Protection Scheme (HPS) applies, your insured share and the actual coverage or claim conditions. If other mortgage insurance or loan-protection arrangements exist, check their actual benefits before counting the same liability twice.
What resources can be subtracted when estimating the gap?
Depending on your circumstances, these may include cash and deposits available to the family, existing life-insurance death benefits after checking the actual policy terms, employer-provided group insurance (recognising that employment-related cover may change or end), and CPF savings distributed according to CPF nomination rules or the applicable distribution process if there is no valid nomination.
Does a larger protection estimate mean I should buy more insurance?
No. A larger protection estimate does not automatically mean that buying more insurance is the right next step. Premium affordability, existing coverage, other financial priorities and policy terms all matter. The purpose of the calculation is to make the discussion more transparent, not to turn a formula into a product recommendation.
Key Takeaways
- There is no universal life-insurance amount or salary multiple that is right for everyone in Singapore.
- Estimate the need from dependants’ living costs, relevant liabilities and planned education support rather than starting with a product.
- Subtract resources that would actually be available, such as accessible savings and existing life-insurance benefits after checking their terms.
- Check HPS, CPF nomination arrangements and other existing protection before counting the same need twice.
- The result is a planning estimate, not an automatic recommended sum assured; affordability, benefit definitions and personal circumstances still matter.
Sources
- Assessing your insurance needs - MoneySense (accessed 2026-08-27)
- Financial advisory process - MoneySense (accessed 2026-08-27)
- Claiming under the Home Protection Scheme - CPF Board (accessed 2026-08-27)
- Making a CPF nomination - CPF Board (accessed 2026-08-27)
About Danny
Danny Chua is a Financial Consultant Representing Prudential Assurance Company Singapore (Pte) Limited. MAS Representative Number CCS300848890. Qualification: BSc. Pharm. Sci.. Read more about Danny.
Related Guidance
- Family Protection Insurance Singapore
- How family protection needs change across life stages
- Term vs whole-of-life cover for family protection
- How guaranteed and non-guaranteed insurance benefits differ
- Insurance Policy Review Singapore — Gaps, Overlaps & Costs
- How to verify a financial consultant in Singapore
- What Is a CPF Nomination and How Is It Different From a Will?
- Family Protection Plan Insurance: What to Understand Before You Decide
- How to Calculate Your Life Insurance Needs in Singapore: A Step-by-Step Coverage Gap Formula
Prudential Assurance Company Singapore (Pte) Limited (PACS) is the insurer referred to in this disclaimer. Investment products are subject to investment risks including the possible loss of the principal amount invested. The figures stated relating to PACS products are for illustrative purposes only. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. We recommend that you seek advice from a PACS Financial Consultant before making a commitment to purchase a Prudential policy.
This advertisement has not been reviewed by the Monetary Authority of Singapore. Investment products are subject to investment risks including the possible loss of the principal amount invested. The information presented is for your information only and does not consider specific investment objectives, financial situation or needs of any person. Seek advice from a Prudential Financial Consultant before making a commitment. This is Danny Chua's personal professional website and is not Prudential's official corporate website.